How Purchase Budget and Total Cost Shape Mattress Buying Decisions
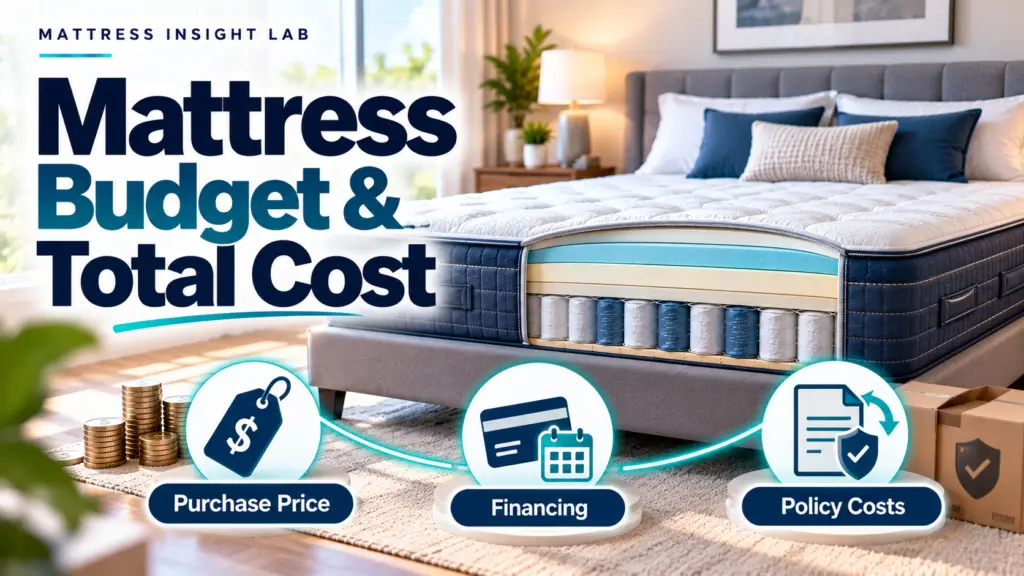
A mattress purchase is easier to evaluate when three different financial views are kept separate: (1) the transaction or cash-equivalent price, (2) the financing overlay if credit is used, and (3) contingent policy costs that arise only if a return, exchange, or warranty event occurs. The financing view is not an additional purchase price: it is another way of describing how the same transaction is paid for.
This guide treats the mattress purchase as a financial transaction to be evaluated, not as a brand-price ranking. It does not cover personal debt management, credit-score strategy, mattress durability science, or general comfort evaluation. Where those topics affect cost, they are mentioned only to the extent that they change what a buyer actually pays.
What Does “Total Mattress Cost” Actually Mean?
“Total mattress cost” can mean different things. For comparison, start with the transaction price of the exact goods and services. If credit is used, add a separate financing overlay showing the applicable credit terms. Then record contingent policy costs separately. Do not add the transaction price to a closed-end loan’s total of payments; total of payments is a financed-payment view of the transaction, not a second mattress purchase price.
The three layers behave differently:
- Transaction / cash-equivalent price — the price of the exact mattress configuration, required support, applicable taxes, and charged services after discounts that actually apply. The amount physically due at checkout can be lower if part of the transaction is financed.
- Financing overlay — the credit terms used to pay for that transaction. For applicable closed-end credit, Regulation Z separates amount financed, finance charge, APR, payment schedule, and total of payments. [1] [2] Open-end/store-card credit and BNPL should be evaluated under their own terms rather than forced into the same template.
- Contingent policy costs — return, exchange, or warranty-related costs that occur only if a policy condition is triggered. These are risk exposures, not guaranteed purchase costs.
Not every purchase uses financing or triggers a policy cost. A cash buyer who keeps the mattress may experience only the transaction price. A financed buyer pays the transaction through a credit arrangement and may also face credit costs. A return or warranty event can add separate contingent costs. Simply adding certain and contingent costs without probability or scenario assumptions can misrepresent expected cost; displaying them separately is usually clearer for consumer comparison.
What Is the Advertised Mattress Price?
The advertised price is a starting reference, not necessarily the price of the configuration you intend to buy. An advertised price may correspond to a particular size or base configuration; the exact model, size, height, firmness option, support requirement, promotion, and service package can change the transaction price.
Treat the advertised price as the entry point to a comparison, not the comparison itself.
What Is the Transaction Price, and What May Be Due at Checkout?
Transaction price is the cash-equivalent price of the exact mattress configuration, required support, applicable taxes, and charged services after discounts that actually apply. The amount due at checkout can be lower when the buyer makes a down payment, first BNPL installment, or other partial payment and finances the remainder. Keep the transaction price separate from the day-one cash outflow.
Delivery, setup, and old-mattress removal may be included at no additional charge depending on the seller and purchase channel. Verify whether each service is included before adding it as a cost.
What Is the Total Repayment Cost if the Purchase Is Financed?
Financing can change the cost of paying for the transaction, but the right comparison depends on the credit type. For closed-end installment credit, Regulation Z separates amount financed, finance charge, APR, payment schedule, and total of payments. The finance charge is the dollar cost of credit and already includes interest plus certain credit-related charges, so interest must not be added again as a separate component. [1] [2] For open-end/store-card credit, repayment cost depends on balance and repayment behavior; there may be no predetermined total of payments. [7] BNPL is a type of installment loan; many common plans are interest-free but can impose late fees or other consequences. [3] [4]
Do not assume every financing offer charges interest, and do not treat “0% APR” and “no interest if paid in full” as equivalent. A true 0% promotion and a deferred-interest offer can produce very different outcomes if a balance remains at the end of the promotional period. [6]
What Are Contingent Costs Such as Return, Exchange, or Warranty Charges?
Contingent costs occur only if the buyer returns, exchanges, or files a warranty claim. They are risk exposure, not certain purchase costs. Return and exchange fees vary by seller, and warranty remedy costs vary by warranty terms.
Do not add a return fee to your total cost if you keep the mattress. Do not add warranty claim costs if no claim occurs. Record them separately as exposure.
Why Should Future Replacement Cost Be Treated as a Scenario Rather Than an Automatic Purchase Cost?
ASTM F1566 provides comparative mattress durability-related methods and explicitly states that the resulting data are for comparative analysis with no pass/fail criteria applicable. [9] It does not convert laboratory results into a universal number of consumer-use years. A defensible cost-per-year calculation therefore needs product-specific service-life assumptions or data that are clearly identified as such.
Purchase price and construction type do not establish a predictable replacement interval, and no cost-per-year figure can be derived from them without that product-specific data. Treat future replacement as a scenario to plan for, not a guaranteed amount to add to the current transaction price.
Why Is This Separation More Useful Than One Oversized “Total Ownership Cost” Number?
Separating the transaction price, financing terms, and contingent policy exposure makes the comparison easier to audit. A single number can be constructed for a defined scenario — for example best case, worst case, or an expected-cost model with explicit probabilities — but simply adding guaranteed and contingent costs without assumptions can misrepresent expected cost.
How Should a Mattress Budget Be Set Before Products Are Compared?
A mattress budget is not a mattress-only sticker price. It is the maximum all-in transaction price the buyer is willing to accept for the usable setup, plus a separate tolerance for financing cost and contingent policy risk. Setting the ceiling before comparing products prevents the mattress itself from consuming money required for compatible support or necessary services.
What Is the Maximum All-In Transaction Price the Buyer Is Willing to Accept?
The maximum all-in transaction price is the ceiling for the exact configuration, required support, applicable taxes, and charged services after valid discounts. If financing is allowed, set a separate limit for acceptable credit cost rather than confusing monthly affordability with transaction value.
Which Costs Are Required for the Mattress to Be Used Correctly?
Required costs depend on the exact mattress and the buyer’s existing setup. A compatible support system may be required; delivery, setup, and removal may or may not be charged. Support-system compatibility is mattress-specific, and delivery inclusion is seller-specific.
Do not assume every mattress purchase requires a new foundation, and do not assume delivery, setup, or removal is paid separately.
Which Add-Ons Are Optional Preferences?
Toppers, pillows, premium sheets, luxury bedding, and similar items are optional preferences unless the buyer would purchase them independently. Optional add-ons inflate the required purchase cost if they are added without a corresponding need.
A mattress protector belongs in the required budget only if it is required by the seller, manufacturer, trial terms, or warranty terms for the exact purchase; otherwise it is a personal-protection choice. No universal protector requirement should be assumed.
Is Financing Allowed Within the Buyer’s Budget Rules?
Financing is a budget rule, not a default. For a closed-end installment loan, compare amount financed, APR, finance charge, payment schedule, and total of payments rather than focusing only on the monthly payment. [1] For open-end/store-card credit, review APR, promotional terms, fees, minimum-payment consequences, and the repayment plan because final cost depends on how the balance is repaid. [7] For BNPL, read the specific installment schedule, interest terms, and fees. [3] [4]
Do not compare financing solely by monthly payment, and do not treat “0% APR” and “no interest if paid in full” as identical.
How Much Contingent Return or Exchange Cost Is the Buyer Willing to Accept?
Return and exchange fees vary by seller. The buyer should set a tolerance for contingent risk before purchase. Return and exchange financial risk must be checked from the exact seller and purchase channel.
Do not assume returns are free, and do not treat trial length itself as financial value.
Why Should Budget Be Applied to the Complete Chosen Configuration Rather Than a Price Tier Label?
Price varies by exact configuration, not by a universal tier label. Budget should be applied to the specific model, size, height, and required support. No supplied evidence establishes that budget tiers correspond to durability or comfort levels.
Why Must the Exact Mattress Configuration Be Priced Before Comparing Options?
A base price cannot be compared with a fully configured competitor. The exact model, size, height, and options must be priced before any comparison is meaningful. Within a current product line, price varies by size and model, and promotions apply to specific configurations.
What Is the Exact Model?
The exact model must be identified before any price comparison. Substantial price variation exists among different mattress models within the same size, so model choice materially changes price.
What Size Is Being Purchased?
Size can change price within a product line. A current product line can show different Queen and King prices for the same model. No universal Queen-to-King multiplier is established, so the exact size must be priced.
Does Firmness or Height Selection Change the Price?
Firmness and height options may change the price; the exact configuration must be priced. Configuration options are part of the exact product being priced.
Are Split Sizes or Specialty Configurations Priced Differently?
Split sizes and specialty configurations may be priced differently; the exact configuration must be priced. Specialty configurations are part of the exact product being priced.
Which Promotion Applies to That Exact Configuration?
Promotion eligibility must be verified for the exact configuration. FTC guidance applies ordinary truthfulness standards to price-comparison and sale-price claims, so the actual transaction price and the basis of the advertised discount are the relevant comparison. [8]
Do not treat a percentage-off label as evidence of good value.
Why Should Product Prices Be Rechecked at the Time of Purchase?
Prices are time-sensitive. Current listings must be rechecked at the time of purchase. Any specific figure drawn from a current seller listing is a current, product-specific example, not a category norm.
Does Mattress Size Determine How Much More You Will Pay?
Size can change price within a product line, but there is no universal multiplier that applies across every mattress and accessory. The exact seller configuration must be used.
Can Queen and King Prices Differ Within the Same Mattress Model?
Yes — within a current product line, Queen and King can be priced differently. Size alone does not determine price; model choice also materially changes price.
Is the Queen-to-King Price Difference the Same Across Every Mattress?
The reviewed evidence does not establish a universal Queen-to-King price difference. Current product listings demonstrate size effects within a product line but do not establish one stable market-wide ratio. Any “King costs X% more than Queen” statement would require current product-specific pricing for the exact choices being compared.
Can California King Cost the Same as King in One Product and Differ in Another?
Pricing between King and California King can vary by product; the exact configuration must be priced. Size-price relationships are product-specific.
Why Should Accessories and Foundations Be Repriced Separately Rather Than Applying a Mattress-Size Multiplier?
Accessories and foundations are separate purchase items with their own pricing; a mattress-size multiplier does not apply to them. Support components can be distinct purchase items. No supplied evidence establishes that larger sizes universally increase every accessory cost.
Why Should the Exact Seller Configuration Be Used Instead of a Generic “Larger Beds Cost X% More” Rule?
The reviewed evidence does not establish a generic “larger beds cost X% more” rule. Current product listings demonstrate size effects within a product line but do not establish a market-wide ratio. Use the exact seller configuration for the exact choices being compared.
Which Support-System Costs Are Actually Required for the Mattress?
A compatible support system can be a separate purchase, but whether it is required depends on the exact mattress and the buyer’s existing setup. Support cost should be determined before setting the maximum mattress-only price.
Can the Existing Platform, Foundation, or Adjustable Base Be Used?
The existing support system may be usable if it satisfies the exact mattress requirements. Support components can be distinct purchase items; whether a new one is required depends on the existing setup.
What Slat, Center-Support, or Base Requirements Does the Exact Mattress Specify?
The exact mattress specifies compatibility requirements; these must be checked against the existing setup. Support components can be distinct purchase items with mattress-specific requirements.
Is a New Foundation Required or Merely Offered as an Add-On?
A new foundation is required only if the existing system does not satisfy the exact mattress requirements; otherwise it is an add-on. Support is a separate cost only when the existing system does not satisfy requirements.
Is an Adjustable Base Necessary for the Intended Use or Optional?
An adjustable base is necessary only if compatibility or the buyer’s requirements make it necessary; otherwise it is optional. No supplied evidence establishes that an adjustable base is a required mattress cost universally.
What Is the Cost of Correcting an Incompatible Existing Setup?
The cost of correcting an incompatible setup depends on the exact mattress requirements and the specific correction needed. Support components can be distinct purchase items with product-specific pricing.
Why Should Support Cost Be Determined Before Setting the Maximum Mattress-Only Price?
Required support cost is part of the all-in transaction price. Determining it first prevents the mattress itself from consuming money required for its usable setup. Required support may increase the all-in transaction price.
Which Accessories Belong in the Mattress Budget—and Which Are Optional?
Accessories belong in the mattress budget only when the buyer would actually purchase them independently. Every accessory should be added only when the buyer would actually purchase it.
Are New Fitted Sheets Required Because the Mattress Size or Depth Changed?
New fitted sheets may be required if mattress size or profile changed; otherwise they are optional. Fitted sheets should be compatible with the mattress’s nominal size and actual profile/pocket-depth requirement, not numerically identical to every mattress dimension. Unusual depth does not by itself establish that sheets will cost more.
Is a Mattress Protector Required by the Seller or Chosen for Personal Protection?
A mattress protector belongs in the required budget only if it is required by the seller, manufacturer, trial terms, or warranty terms for the exact purchase; otherwise it is a personal-protection choice. No universal protector requirement should be assumed.
Is an Allergen Encasement Needed for a Specific Exposure-Control Goal?
An allergen encasement is needed only if the buyer has a specific exposure-control goal; otherwise it is optional. No supplied evidence establishes that an allergen encasement is always required.
Is a Topper Actually Required for the Mattress Being Considered?
A topper is required only if the buyer would purchase it independently; otherwise it is optional. No supplied evidence establishes that a topper is a required mattress cost.
Are New Pillows or Bedding Independent Purchases Rather Than Mattress Costs?
New pillows and bedding are independent purchases unless the buyer would purchase them as part of the mattress transaction. No supplied evidence establishes that pillows, premium sheets, or luxury bedding are required mattress costs.
Why Should Every Accessory Be Added Only When the Buyer Would Actually Purchase It?
Adding accessories the buyer does not need can inflate the transaction price without creating equivalent personal value. Bundled accessories should be assigned value only to the extent that the buyer would otherwise purchase or meaningfully value them; compare the bundle price with the price of the configuration actually needed.
How Should Delivery, Setup, and Old-Mattress Removal Be Priced?
Delivery, setup, and old-mattress removal cannot automatically be added as paid fees. Whether each service is included, optional, or charged depends on the seller and purchase channel. Do not assume “White Glove” includes the same services or carries the same price across sellers; verify the actual service description.
Is Basic Shipping Included?
Basic shipping may be included; verify from the exact seller and purchase channel. Delivery inclusion is seller-specific.
Is In-Room Placement or Setup Included?
In-room placement or setup may be included; verify from the exact seller and purchase channel. Setup inclusion is seller-specific.
Is White Glove Service Included, Optional, or Unavailable?
White Glove service may be included, optional, charged, or unavailable depending on the seller and channel. Verify the seller’s actual service description rather than assuming a standard bundle of services or price.
Is Old-Mattress or Foundation Removal Included?
Old-mattress or foundation removal may be included; verify from the exact seller and purchase channel. Removal inclusion is seller-specific.
Which Old-Bed Components Are Excluded From Haul-Away?
Haul-away eligibility may exclude certain components; verify from the exact seller and purchase channel. Removal eligibility is seller-specific.
Why Should the Service Description Be Checked Rather Than Assuming “Free Delivery” or “White Glove” Has One Universal Meaning?
Service descriptions vary by seller and purchase channel; verify each service’s inclusion status. “Free shipping” does not mean there are no other transaction costs.
Should Mattress Prices Be Compared by Online Versus In-Store Channel?
The reviewed evidence does not establish that online mattresses are inherently cheaper or that stores inherently charge higher markups. Compare exact offers instead. Final price, delivery terms, trial terms, warranty validity, and bundle contents must be compared from each seller.
What Is the Final Price for the Exact Mattress From Each Seller?
The final price for the exact mattress must be obtained from each seller. Final pricing depends on manufacturer strategy, promotions, seller margins, services, returns, channel-specific products, and current commercial terms. No supplied evidence establishes a channel-cost advantage.
Are Delivery and Setup Terms the Same?
Delivery and setup terms vary by seller; verify each. Delivery and setup inclusion is seller-specific.
Are Trial and Return Terms the Same?
Trial and return terms vary by seller; verify each. Return costs vary materially by seller.
Is the Warranty Valid Through That Seller?
Warranty validity depends on the seller and purchase channel; verify each. Warranty terms are specific to the exact warranty cited.
Are Any Accessories or Services Bundled Into One Offer?
Bundles must be evaluated by whether the included items would otherwise be purchased. Bundled accessories should be assigned value only to the extent that the buyer would otherwise purchase or meaningfully value them; compare the bundle price with the price of the configuration actually needed.
Why Should “Online Is Cheaper” or “Stores Charge More” Not Be Used as a Universal Buying Rule?
The reviewed evidence does not establish that online mattresses are inherently cheaper or that stores inherently charge higher markups. Final pricing depends on manufacturer strategy, promotions, seller margins, services, returns, channel-specific products, and current commercial terms. A stable channel-cost advantage would require same-product, same-date, same-service transaction comparisons.
How Should Mattress Sales, Discounts, and Bundles Be Evaluated?
A percentage-off label is pricing information, not a value verdict. The relevant comparison is the actual transaction price and the product received. Audit promotions by comparing the actual transaction price, the reference price, configuration eligibility, and bundle contents.
What Is the Actual Checkout Price After the Promotion?
The actual transaction price after the promotion is the relevant figure. FTC truthfulness standards apply to price comparisons and sale pricing. [8]
What Reference Price Is the Discount Being Compared With?
The reference price must be identified to evaluate the discount. The basis of the discount is the relevant comparison, not the discount percentage alone.
Is the Promotion Available for the Exact Model, Size, and Configuration?
Promotion eligibility must be verified for the exact configuration. Eligibility is configuration-specific.
Would the Buyer Purchase the Bundled Accessories Without the Bundle?
Bundled accessories should be assigned value only to the extent that the buyer would otherwise purchase or meaningfully value them; compare the bundle price with the price of the configuration actually needed. Evaluate bundle contents against actual needs.
Does a “Free” Item Change Any Other Price or Condition?
A “free” item may be conditioned on other terms; verify the full transaction. The actual transaction is the relevant comparison.
Why Does a Large Percentage-Off Label Not Prove That One Mattress Is Better Value?
The reviewed evidence does not establish that a larger discount indicates a better purchase. Truth-in-advertising principles apply to price comparisons and sale pricing; discount magnitude is not a value score. A defensible value comparison would require the actual final price plus product-, policy-, and requirement-level comparison.
How Can Financing Change the Total Mattress Cost?
Financing can change the cost of paying for the mattress, but the right comparison depends on the financing structure. For applicable closed-end credit, review amount financed, finance charge, APR, payment schedule, and total of payments. [1] For open-end/store-card credit, there may be no predetermined total repayment because cost depends on balance, rates, fees, and repayment behavior. [7] For BNPL, review the specific installment schedule, interest, and fee terms. [3] [4]
What Is the Cash Purchase Price?
The transaction or cash-equivalent price is the baseline value of the purchase before financing structure is applied. It is not automatically the amount physically paid on checkout day when a down payment or partial installment is used.
What Amount Is Being Financed?
For applicable closed-end credit, amount financed is the net amount of credit extended to or on behalf of the consumer. Regulation Z treats it as distinct from the finance charge and total of payments. [1]
What Interest Rate Applies, and What Is the APR?
The interest rate is the borrowing rate, while the APR is a broader annualized measure that incorporates the interest rate plus applicable loan fees. They are related but not interchangeable. CFPB updated consumer guidance in August 2026 to make this distinction explicit. [5]
What Finance Charges or Fees Apply?
For applicable closed-end credit, the finance charge is the dollar cost of consumer credit. It includes interest and certain credit-related fees; do not add “interest + finance charge” as though they were independent totals. [2]
What Is the Total of All Required Payments?
For applicable closed-end credit, total of payments is the sum of the scheduled payments disclosed in the payment schedule. [1] It is useful for comparing a fixed installment obligation, but it is not a universal disclosure for every form of mattress financing.
How Can Late Fees or Other Loan Charges Increase Cost?
Late fees and other contractual consequences can increase the cost of financing or create additional risk. CFPB says many BNPL loans do not charge interest, while most charge late fees for missed payments. [3] [4]
Why Should Monthly Payment Never Be Compared Without Total Repayment?
Do not compare financing solely by monthly payment. For closed-end credit, use the full Regulation Z disclosure set, including APR, finance charge, amount financed, payment schedule, and total of payments. [1] For open-end credit, compare APR, fees, promotional terms, minimum-payment effects, and the repayment plan because the final cost is behavior-dependent. [7]
Which Financing Type Is Being Used?
Before comparing financing cost, identify the credit structure. Regulation Z separates open-end credit from closed-end credit, and the disclosure framework differs. [7]
How Should a Closed-End Installment Loan Be Compared?
For applicable closed-end installment credit, review the amount financed, finance charge, APR, payment schedule, and total of payments. Section 1026.18 applies specifically to closed-end consumer credit and defines total of payments as the sum of scheduled payments. [1]
How Should a Retail or Store Credit Card Be Compared?
A store credit card is open-end credit. There may be no fixed future total of payments because cost depends on the outstanding balance, APR, fees, promotional terms, and repayment behavior. Review the card agreement and the specific promotion rather than importing the closed-end loan template. [7]
How Should BNPL Be Compared?
BNPL is a type of installment loan. A common short-term form splits a purchase into four interest-free biweekly payments, but products vary and may impose late fees or other consequences. [3] [4] Read the exact payment schedule and fee/interest terms.
Are 0% APR, Deferred Interest, and Buy Now Pay Later the Same Thing?
True 0% APR, deferred interest, and buy-now-pay-later are distinct financing structures. The exact credit agreement overrides mattress-seller marketing language.
What Does a True 0% APR Promotional Period Mean?
A true 0% APR promotional period does not add interest based on the promotional balance during that period. If a balance remains when the promotional period ends, interest generally begins prospectively under the post-promotion terms rather than being imposed retroactively for the promotional period. [6]
What Does “No Interest if Paid in Full” Mean Under Deferred Interest?
Under deferred-interest terms, missing the payoff requirement can cause interest tied to the promotional period to be charged. Deferred interest is not the same as true 0% APR.
What Can Happen if a Deferred-Interest Balance Is Not Fully Paid by the Deadline?
Under deferred-interest terms, failing to pay the promotional purchase in full by the deadline can cause interest dating back to the original purchase to be charged, subject to the agreement. [6] A 0% APR promotion also does not necessarily eliminate late fees or other consequences for violating the agreement.
How Does a Typical Short-Term BNPL Plan Differ?
BNPL is a form of installment credit. A common short-term structure uses four interest-free payments, but CFPB notes that many BNPL products can charge late fees for missed payments. [3] [4] Longer-term installment products may use different interest and fee structures.
Can BNPL Still Carry Late Fees or Other Consequences?
Yes — BNPL plans can carry late fees or other consequences. BNPL is not automatically free.
Why Should the Exact Credit Agreement Override Mattress-Seller Marketing Language?
The exact credit agreement is the controlling document; marketing language may not reflect the actual terms. Consumer-credit disclosures are the relevant source for financing terms.
How Do Sleep Trial, Return, and Exchange Terms Create Financial Risk?
Trial and return terms create contingent financial risk. The maximum realistic cost of rejecting a poor-fit mattress must be determined before purchase. Return and exchange financial risk must be checked from the exact seller and purchase channel.
When Does the Trial Begin?
The trial start date is seller-specific; verify from the exact seller. Trial terms vary by seller.
Is There a Required Minimum Use Period?
A required minimum use period is seller-specific; verify from the exact seller. Trial terms vary by seller.
Is There a Return Pickup, Shipping, or Processing Fee?
Return fees are seller-specific; verify the exact policy. For example, Saatva currently charges a $99 processing fee for mattress returns and exchanges during its 365-night trial. [13] Do not assume returns are free.
Does an Exchange Use the Same Fee Structure?
Exchange fee structure is seller-specific; verify from the exact seller. Return and exchange terms vary by seller and may be treated differently.
Are Adjustable Bases, Foundations, Bedding, or Other Bundle Items Covered by the Same Trial?
Trial coverage of bundle items is seller-specific; verify from the exact seller. Trial terms vary by seller.
Are Any Original Delivery or Service Fees Non-Refundable?
Refund scope is seller-specific; verify from the exact seller. Return terms vary by seller.
Why Should Return Cost Be Recorded as a Risk Exposure Rather Than Added Automatically to the Purchase Total?
Return cost applies only if a return occurs; it is risk exposure, not a certain purchase cost. Return costs vary by seller and apply only to qualifying returns. Do not add the return fee to your total cost if the mattress is kept.
How Can Warranty Terms Create Future Costs Even When Coverage Is Long?
Warranty duration and coverage terms describe how long coverage lasts and who pays what. Current mattress warranties provide real examples of purchaser-paid transportation, inspection, processing, prorated/deductible, and upgrade costs even when coverage remains active. [10] [11] [12] Evaluate warranty value through covered defects, remedies, exclusions, and purchaser costs — not duration alone.
Which Defects Are Covered?
Covered defects are warranty-specific; verify from the exact warranty. Warranty terms are specific to the exact warranty cited.
Is Repair or Replacement Free During the Relevant Period?
Repair or replacement may carry purchaser costs; verify from the exact warranty. Warranty duration does not equal cost-free future service.
Who Pays Transportation or Freight?
Transportation or freight responsibility is warranty-specific; verify from the exact warranty. Transportation associated with qualifying repair or replacement can remain the purchaser’s responsibility; Tempur-Pedic and Sealy currently place certain transportation costs on the purchaser. [10] [11]
Can an Inspection Fee Apply?
An inspection fee may apply; verify from the exact warranty. An inspection fee may apply pending claim approval. Tempur-Pedic and Sealy currently require an upfront inspection fee when an inspector is required, with reimbursement if the claim is covered. [10] [11]
Is Coverage Prorated or Subject to Processing Charges?
Coverage may be prorated or subject to processing charges; verify from the exact warranty. Processing fees and replacement-option cost schedules may apply; Saatva currently uses a $149 processing fee under certain post-year-2 warranty remedies and percentage-based replacement options under its Fairness Replacement structure. [12]
Does an Upgrade Require Paying the Difference?
Upgrade terms are warranty-specific; verify from the exact warranty. Replacement-option cost schedules may apply.
Does a Replacement Restart the Warranty?
Warranty restart terms are warranty-specific; verify from the exact warranty. Warranty terms are specific to the exact warranty cited.
Why Does Warranty Length Alone Not Reveal the Consumer’s Potential Claim Cost?
Warranty length describes coverage duration; remedy terms describe who pays what. Warranty duration does not equal cost-free future service. A long or lifetime warranty does not guarantee free mattress replacement.
Can Mattress Price or Material Type Predict Long-Term Value?
The reviewed evidence does not establish that higher price or a specific material type predicts greater durability or longer service life. Require actual durability evidence before predicting replacement. “Premium,” “high-quality,” and “luxury” should not be converted into automatic long-term value.
Does Higher Mattress Price Prove Greater Durability?
The reviewed evidence does not establish that higher price proves greater durability. Price can reflect materials, size, construction, branding, services, features, distribution strategy, or other commercial factors. A price-to-durability relationship would require product-specific durability data under comparable use conditions.
Does Latex, Hybrid, Foam, or Innerspring Construction Establish a Universal Lifespan?
The reviewed evidence does not establish that any construction type has a universal lifespan. ASTM F1566 provides comparative methods and states that no universal pass/fail criteria apply. [9] A construction-to-lifespan relationship would require product-specific service-life data under comparable use conditions.
Can Material Specifications Contribute Useful Durability Evidence Without Predicting Years of Service?
Material specifications can contribute useful durability evidence within their scope, but they do not predict years of service. ASTM F1566 is comparative and does not convert results into consumer-use years. [9]
What Can Standardized Complete-Mattress Durability Testing Show?
Standardized complete-mattress durability testing can show comparative durability, firmness retention, and surface deformation data. ASTM F1566 data are intended for comparative analysis, not direct service-life prediction. [9]
Why Should “Premium,” “High-Quality,” and “Luxury” Not Be Converted Into Automatic Long-Term Value?
Premium labels describe positioning, not durability or service life. ASTM F1566 is comparative and does not convert results into consumer-use years. [9] Premium materials do not automatically reduce replacement risk.
Can You Calculate Mattress Cost Per Year Before Purchase?
The reviewed evidence does not establish a universal mattress service life or a reliable cost-per-year formula. Unverified replacement timing should be presented as a scenario rather than a factual savings calculation.
What Service-Life Number Would Be Needed to Calculate Cost per Year?
A defensible cost-per-year calculation requires a defensible service-life estimate for the exact product. ASTM F1566 is comparative and does not convert results into consumer-use years. [9]
Is That Number Based on the Exact Mattress or a Generic Internet Lifespan Estimate?
A defensible cost-per-year calculation requires product-specific service-life data, not a generic estimate. ASTM F1566 is comparative and does not convert results into consumer-use years. [9]
Does Warranty Length Equal Service Life?
Warranty length describes coverage duration, not service life. Warranty duration does not equal cost-free future service, and standardized durability testing is comparative, not lifespan-predictive.
Does Laboratory Durability Testing Translate Directly Into Years of Household Use?
Laboratory durability testing provides comparative data, not a direct conversion to years of household use. ASTM F1566 states that its data are for comparative analysis and that no pass/fail criteria apply. [9]
Why Should Unverified Replacement Timing Be Presented as a Scenario Rather Than a Factual Savings Calculation?
The reviewed evidence does not establish a universal mattress service life or a reliable cost-per-year formula. A defensible cost-per-year calculation requires product-specific service-life data under comparable use conditions. Purchase price and construction type do not establish a predictable replacement interval.
Should Different Types of Sleepers Be Given Different Mattress Budgets?
The reviewed evidence does not establish that demographic labels imply predetermined budget tiers. Budget should follow requirements the buyer has actually identified. Size, support requirements, durability evidence, and desired features can legitimately change the exact configuration.
Why Does “Guest Room” Not Define One Appropriate Mattress Budget?
The reviewed evidence does not establish that guest-room mattresses should receive a predetermined budget tier. A person’s required size, support system, performance attributes, usage frequency, and preferred features can affect the chosen configuration, but those requirements do not translate into one evidence-based dollar amount.
Why Does Being a Couple Not Establish a Required Spending Tier?
The reviewed evidence does not establish that couples should receive a predetermined budget tier. A person’s required size, support system, performance attributes, usage frequency, and preferred features can affect the chosen configuration, but those requirements do not translate into one evidence-based dollar amount.
Why Does Body Weight Not Establish a Dollar Budget?
The reviewed evidence does not establish that body weight translates into a predetermined dollar budget. A person’s required size, support system, performance attributes, usage frequency, and preferred features can affect the chosen configuration, but those requirements do not translate into one evidence-based dollar amount.
How Can Size, Support Requirements, Durability Evidence, and Desired Features Legitimately Change the Exact Configuration?
Size, support requirements, durability evidence, and desired features can change the exact configuration and therefore the price. Configuration affects price, and support can be a separate cost.
Why Should the Budget Be Tied to Requirements the Buyer Has Actually Identified?
A feature is valuable only if it serves a requirement the buyer actually has. Requirements, not labels, determine the budget.
How Should Mattress Budget and Total Cost Be Calculated Before Checkout?
Calculate the transaction price first. Then, if credit is used, evaluate the financing structure as an overlay on that same transaction. Record return/exchange and warranty exposure separately. Scenario totals can be built when assumptions are explicit, but do not double-count the transaction price inside financed repayment.
Record the Exact Mattress Model, Size, Height, and Configuration Price
Record the exact configuration price from the seller. Price varies by size and model within a current product line.
Add Only the Support Components Required for Compatibility
Add only the support components required for compatibility with the exact mattress. Support components can be distinct purchase items.
Add Accessories the Buyer Actually Needs
Add only accessories the buyer would actually purchase. Optional accessories inflate the required purchase cost.
Add Applicable Tax, Shipping, Delivery, Setup, and Removal Charges
Add only the charges that actually apply to the exact purchase. Delivery, setup, and removal inclusion is seller-specific.
Subtract Only Discounts That Actually Apply to the Selected Configuration
Subtract only discounts that actually apply to the selected configuration. FTC truthfulness standards apply to price comparisons and sale pricing. [8]
Record the All-In Transaction Price
The all-in transaction price is the exact configuration price plus required support, needed accessories, applicable taxes and charged services, minus discounts that actually apply. The amount due at checkout may be lower if part of the transaction is financed. Contingent policy costs are recorded separately.
If Financing, Record the Credit Terms Appropriate to That Financing Type
For applicable closed-end credit, record amount financed, finance charge, APR, payment schedule, and total of payments. [1] [2] For an open-end/store-card plan, record APR, fees, promotional terms, and your intended repayment strategy. For BNPL, record the actual installment schedule and any interest or late-fee terms. [3] [4] [7]
Record the Maximum Return or Exchange Cost as a Contingent Risk
Record the maximum return or exchange cost as a contingent risk, not as a certain purchase cost. Return costs vary by seller and apply only to qualifying returns.
Record Material Warranty Claim Costs and Limitations Separately
Record material warranty claim costs and limitations separately from the transaction price. Warranty duration does not equal cost-free future service.
Do Not Add an Invented Future Replacement Cost Without Product-Specific Service-Life Evidence
The reviewed evidence does not establish a universal mattress service life or a reliable cost-per-year formula. A defensible cost-per-year calculation requires product-specific service-life data under comparable use conditions. Purchase price and construction type do not establish a predictable replacement interval.
Compare Competing Mattresses Using the Same Cost Categories
Compare competing mattresses using the same categories: all-in transaction price, financing overlay if used, and contingent policy exposure. Like-for-like comparison requires consistent categories. An advertised price is not necessarily the all-in transaction price.
Choose the Configuration That Meets the Buyer’s Actual Mattress Requirements Within the Accepted Financial Limits
Choose the configuration that meets the buyer’s actual mattress requirements within the accepted financial limits. A feature is valuable only if it serves a requirement the buyer actually has. Price does not prove durability or value.
Sources and References
- CFPB Regulation Z §1026.18 — Content of disclosures. Closed-end amount financed, finance charge, payment schedule, and total of payments.
- CFPB Regulation Z §1026.4 — Finance charge. Definition of finance charge.
- CFPB — What is a Buy Now, Pay Later loan? BNPL as installment credit.
- CFPB — Do BNPL loans have fees? BNPL fee guidance.
- CFPB — Difference between a loan interest rate and APR. Interest rate vs. APR.
- CFPB — Promotional credit-card financing. 0% APR vs. deferred interest.
- CFPB — Regulation Z overview. Open-end and closed-end credit structure.
- FTC — Advertising FAQs. Price comparison and sale-price truthfulness.
- ASTM F1566-14(2021). Mattress durability methods and comparative-analysis scope.
- Tempur-Pedic — 10-Year Mattress and Flat Foundation Limited Warranty. Inspection, transportation, replacement, and upgrade terms.
- Sealy — Mattress and Flat Foundation Warranty. Deductible, inspection, transportation, and replacement terms.
- Saatva — Warranty. Processing fees and replacement options.
- Saatva — 365-Night Trial. Current return/exchange processing fee example.
Final synthesis. Start with the all-in transaction or cash-equivalent price of the exact mattress setup. If financing is used, treat the credit terms as an overlay on that same transaction rather than as a second additive purchase layer. For closed-end credit, use Regulation Z terms such as amount financed, finance charge, APR, payment schedule, and total of payments; for open-end credit or BNPL, use the disclosure structure that actually applies. Keep return, exchange, and warranty costs as contingent policy exposure unless they occur. Price, material type, and construction do not establish a universal service life, so cost-per-year claims require explicit product-specific assumptions rather than an invented lifespan. The most useful budget discipline is to compare exact configurations using the same transaction, financing, and policy-risk categories.